
The Green Sheet Online Edition
October 26, 2026 • 26:10:02
Legal Ease:
US payments, foreign owners: Is that legal?
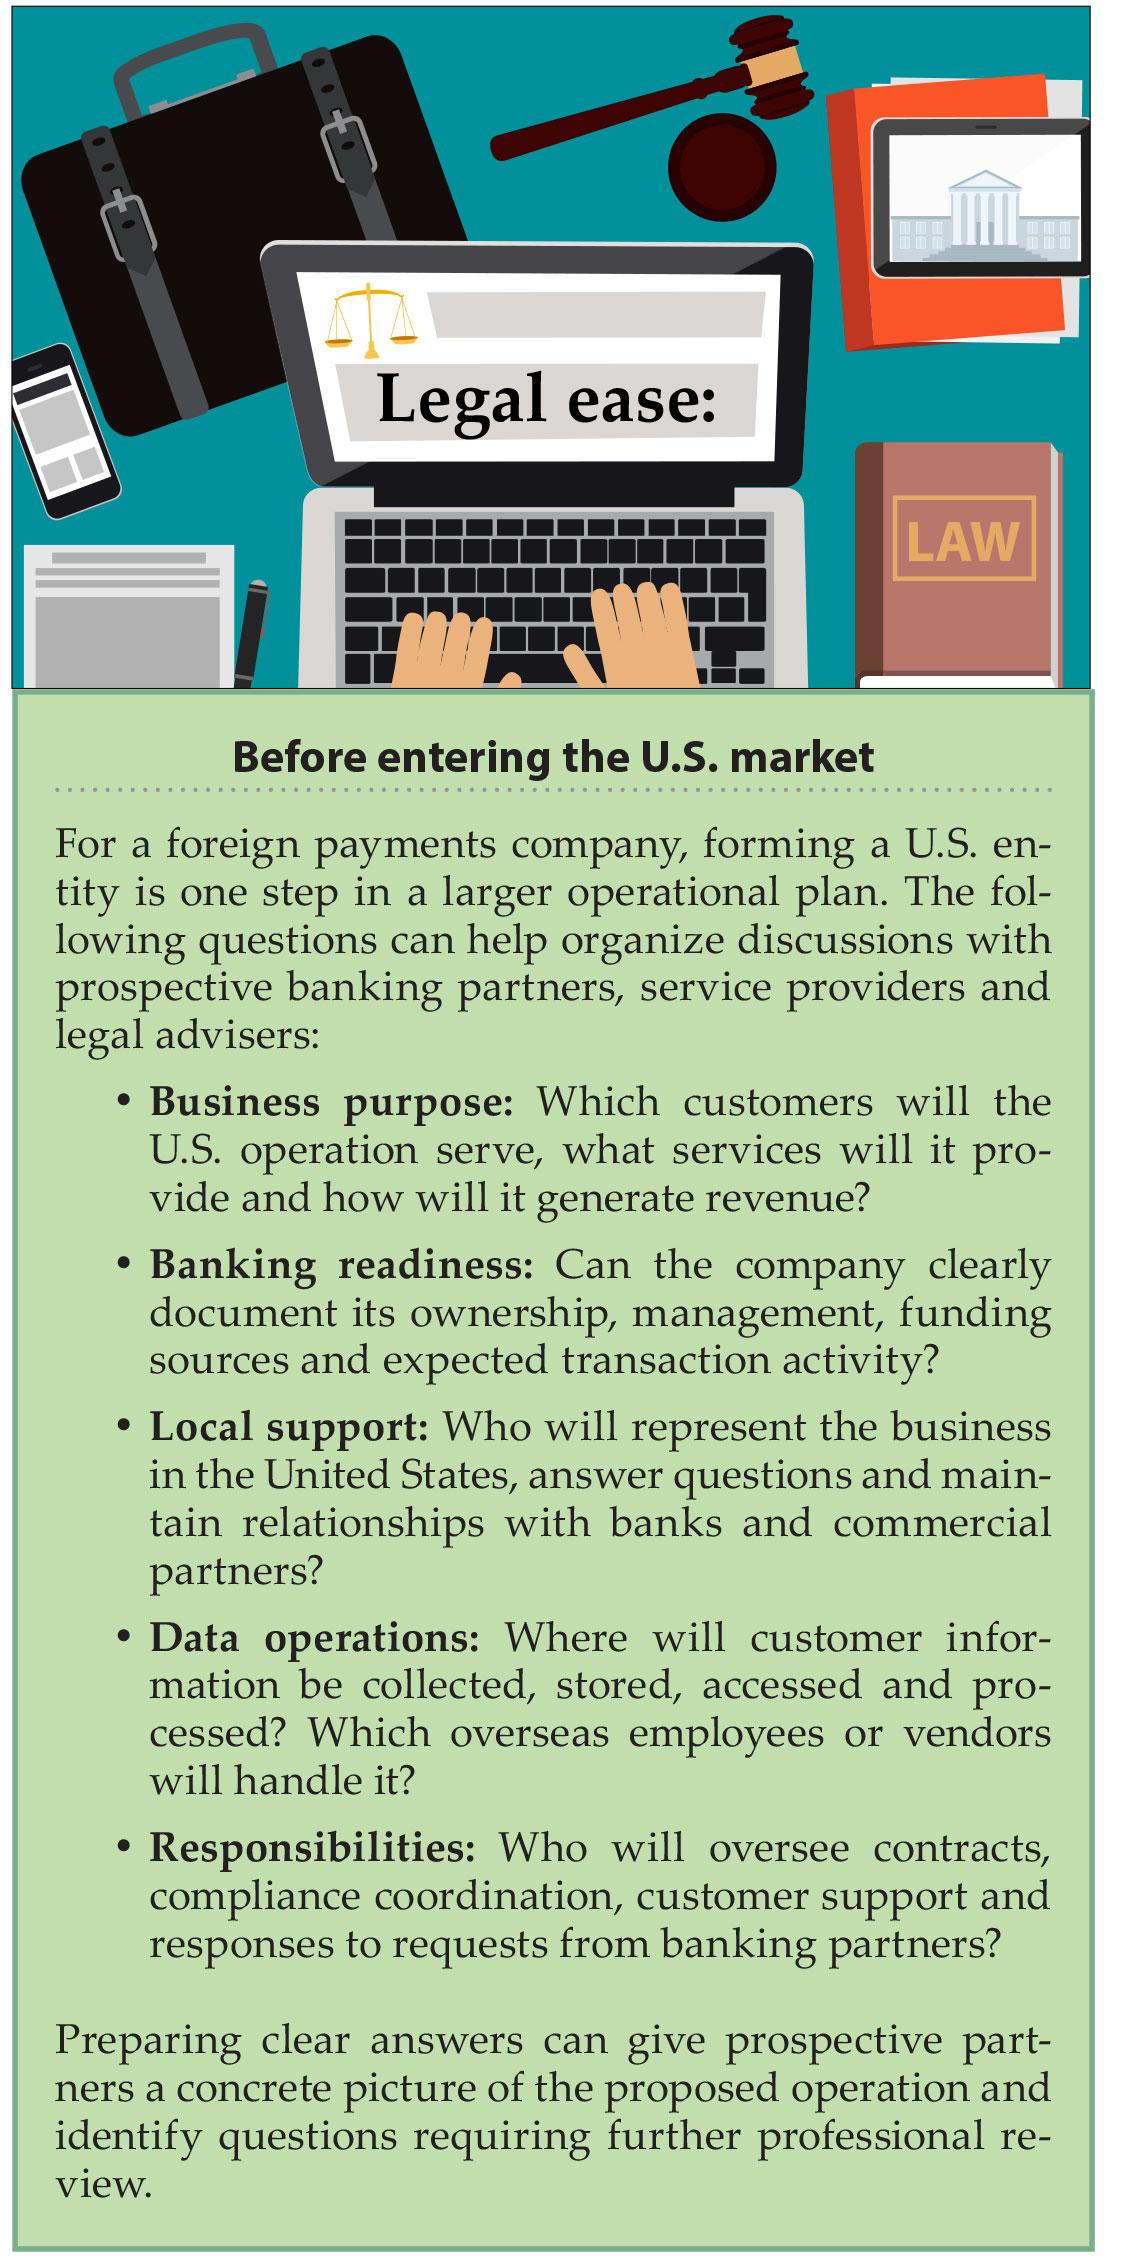
It's a lot easier to start a U.S. payments business from a foreign country than the other way around. In a free country, starting a business should not be complicated. Indeed, in a free country, it is often not much harder for a foreigner to start a business than someone who is a citizen. Some countries discriminate in business against foreigners but the United States does not. This feature of the U.S. market is part of what attracts capital from all over the world and contributes to making the United States the wealthiest country in the world with a $32 trillion GDP.
Apart from investing in the richest country in the world, foreign capital comes to the United States partly because the United States values law and order. Investors, both domestic and foreign, put faith in the real value of the contracts they sign under U.S. law because they expect U.S. courts to deliver impartial justice in the event of a dispute.
Foreign investment in the United States
In the last edition of Legal Ease, I discussed U.S. payments businesses expanding into foreign jurisdictions ("Payments throughout the Americas: Legal issues when taking on the hemisphere," issue 26:09:02, www.greensheet.com/ebooks/gs260902/index.html#p=16 ). In this edition, I take a look at investment going in the other direction: foreign businesses coming to the United States.
This subject interests both foreign and domestic readers, partly because foreign business sometimes comes to America with new ideas. For example, Holland-based Adyen operates in the United States through a U.S. branch of a Dutch bank. This could serve as inspiration for U.S. payments businesses wanting to provide acquiring, issuing and processing services through a chartered bank rather than a sponsored ISO. Another example is Revolut, a UK-based fintech that became a bank in the UK earlier this year and is also obtaining a U.S. OCC bank charter. These and other foreign-based fintechs bring healthy competition to the U.S. market, but they also present a handful of legal issues.
- No legal restrictions on foreign ownership in payments
Setting aside foreign owners subject to U.S. sanctions, as a rule, there aren't restrictions on foreign ownership of U.S. payments business. Subject to exceptions granted on application, nationally chartered banks must have directors that are U.S. citizens. Money transmitters, processors, ISOs and payment facilitators can all get up and running with entirely foreign ownership. This is helpful to foreign payment companies that want to add the US market to their business.
- Banking not so easy
Banking a payments company is never easy, but banking a payments company with foreign owners is even harder. Banks rightfully place foreigners under scrutiny when opening U.S. bank accounts so that the bank does not unwittingly facilitate sanctions evasion or other illegal activity. That said, ordinary (not sanctions-listed) foreigners will find it harder to bank their U.S. companies than U.S. citizens. U.S. banks are sometimes not equipped to manage the risk of underwriting foreign owners as to creditworthiness and other risk factors.
In my previous column about expanding U.S. business to foreign countries I recommended connecting with a local partner to help, if only as a sales rep. The same logic works in-bound. A U.S. partner, director or sales rep will go a long way toward getting a leg-up on rolling out a business domestically. A U.S. director, however, will help a lot with banking, as the U.S. citizen representing the company will assist banks in underwriting the company as a client.
- Cross-border data flows to be legally framed
An established foreign payments business may wish to make use of systems and personnel located outside of the United States to process transactions, manage risk and run the business. U.S. state law requires that a U.S. payments business (domestic or foreign) obtain consent of data subjects before shipping U.S. personal information overseas for processing or any other purpose.
A foreign business setting up shop in the United States should consider the legal framing of its data collection, processing and disclosure to make sure that use of its foreign assets does not put it in violation of U.S. law.
- Make it real
Foreigners should be wary of entering the U.S. market simply to use U.S. banking or access U.S. interchange rates. Depending on the purpose of the business, it may be deemed illegal money laundering, if the US entity has nominee (that is, stooge) directors and has no actual objective business purpose.
If you are a foreign payments business coming to the United States or a U.S. person or business helping the foreign business, be mindful of there being a real business intent before getting going. It always helps to bridge the cultural divide between a foreign business and the U.S. market into which they expand. Not everyone is ready for blocking, tackling and the rough and tumble of operating in a free country.

In publishing The Green Sheet, neither the author nor the publisher are engaged in rendering legal, accounting, or other professional services. If legal advice or other expert assistance is required, the services of a competent professional should be sought. For further information on this article, please contact Adam Atlas, Attorney at Law email: atlas@adamatlas.com, Tel. 514-842-0886.
Notice to readers: These are archived articles. Contact information, links and other details may be out of date. We regret any inconvenience.
